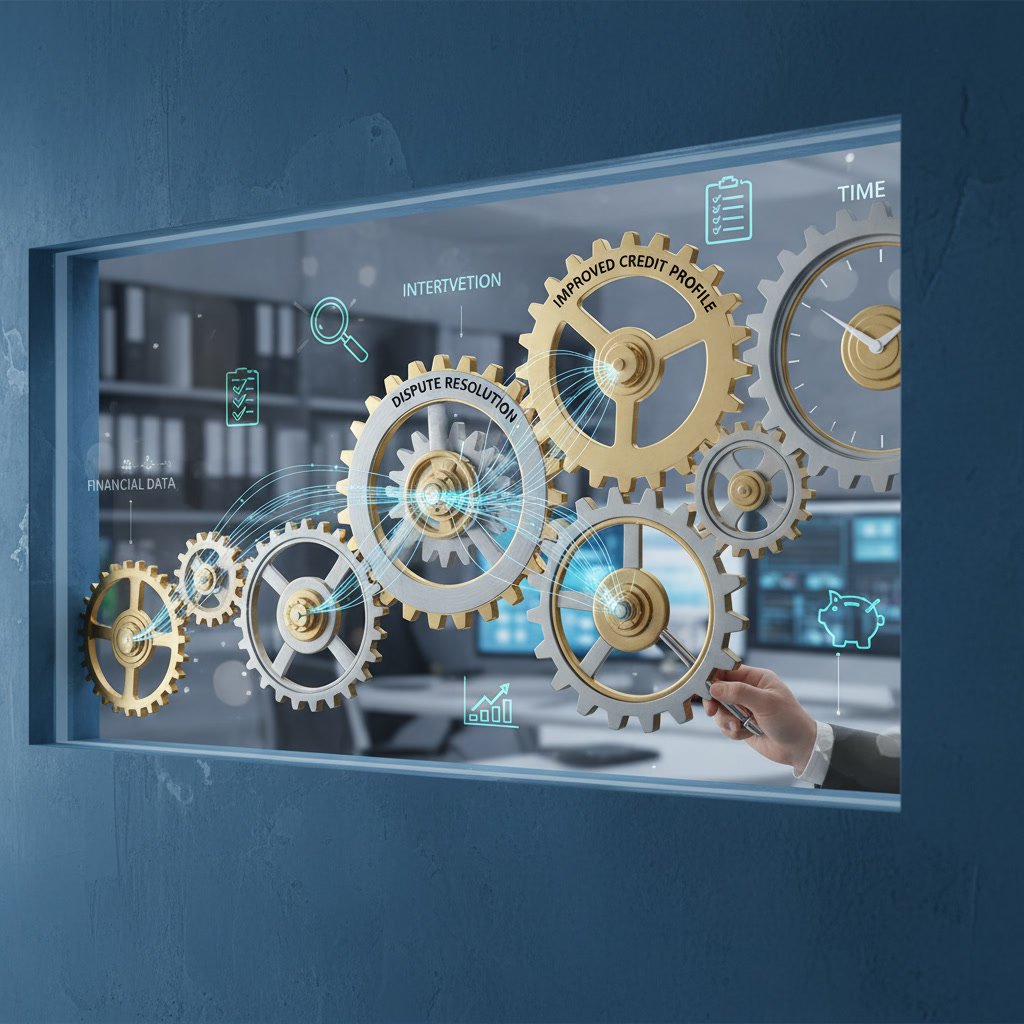
Credit repair is a systematic process of identifying errors, disputing inaccuracies, and improving your credit profile. Most people see initial results in 30 to 45 days, but meaningful improvement typically takes three to six months depending on the complexity of your credit issues. Understanding how credit repair works helps you set realistic expectations and avoid companies that promise overnight fixes.
Why Your Credit Score Matters More Than You Think
Your credit score touches nearly every major financial decision you make. It determines whether you qualify for a mortgage, the interest rate on your car loan, and sometimes even your ability to rent an apartment or secure certain jobs. A difference of just 50 points can mean thousands of dollars in additional interest over the life of a loan.
When your score drops because of errors, late payments, or collection accounts, the financial consequences ripple through your life. Higher insurance premiums, security deposits for utilities, and denied loan applications become routine frustrations. Repairing your credit isn’t just about numbers on a report. It’s about reopening doors that bad credit closed.
The Real Reasons Credit Scores Drop
Credit scores decline for specific, identifiable reasons. Payment history accounts for 35% of your FICO score, so even one late payment can cause a significant drop. Accounts sent to collections, charge-offs, and public records like bankruptcies or tax liens create serious damage that persists for years.
Credit utilization, the ratio of your balances to your credit limits, makes up 30% of your score. Maxing out cards or closing old accounts reduces your available credit and drives this ratio higher. Credit report errors are surprisingly common. The Federal Trade Commission found that one in five consumers has an error on at least one of their three credit reports, and these mistakes can unfairly lower your score.
The Step-by-Step Credit Repair Process
Legitimate credit repair follows a structured, legal process defined by the Fair Credit Reporting Act and the Fair Debt Collection Practices Act. The first step is obtaining your credit reports from all three major bureaus: Equifax, Experian, and TransUnion. You’re entitled to one free report from each bureau every 12 months through AnnualCreditReport.com.
Next comes the detailed audit. Every account, inquiry, and public record must be reviewed for accuracy. You check payment histories, account balances, credit limits, and personal information. Common errors include accounts that don’t belong to you, duplicate accounts, incorrect payment statuses, and outdated negative items that should have been removed.
Once errors are identified, formal disputes are filed with the credit bureaus. Each dispute must include specific information about the error and supporting documentation. The bureaus have 30 days to investigate, contact the creditor or data furnisher, and respond. If the information cannot be verified, it must be removed from your report.
Simultaneously, you may need to dispute items directly with creditors, especially if the bureau’s investigation doesn’t resolve the issue. This dual-track approach often produces better results than relying solely on bureau disputes.
What Happens During the First 30 Days
The first month focuses on gathering information and filing initial disputes. Professional services pull your reports, conduct the audit, and prepare dispute letters. If you’re handling it yourself, this phase requires careful attention to detail and organized record-keeping.
During this period, you should also review your budget and payment habits. Credit repair works best when combined with improved financial behavior. Setting up automatic payments for current accounts prevents new late payments from undermining your repair efforts.
Realistic Timelines for Seeing Results in Texas and Beyond
Simple errors like incorrect personal information or duplicate accounts can be resolved within 30 to 45 days. These quick wins provide immediate score boosts and build momentum. More complex issues like charge-offs, collections, or items requiring multiple rounds of disputes typically take three to six months.
Serious negative items like bankruptcies or foreclosures can’t be removed if they’re accurate and timely. These remain on your report for seven to ten years, though their impact diminishes over time. The focus shifts to building positive credit history that gradually outweighs the negative marks.
In our experience at Quick Tax and Credit Solutions Inc, clients with two to four disputed items see meaningful improvement within 90 days. Those with heavily damaged credit profiles often need six to 12 months of consistent work to achieve their target scores.
The Difference Between DIY and Professional Services
You have the legal right to dispute errors on your own at no cost. The process is straightforward for simple errors and doesn’t require special expertise. Many people successfully repair their own credit by following the procedures outlined on the Consumer Financial Protection Bureau website.
Professional credit repair services bring experience, systems, and persistence. They know which dispute language works best, how to escalate unresolved issues, and how to coordinate disputes across all three bureaus efficiently. For complex cases involving multiple creditors, collections, or legal issues, professional help saves time and often produces better outcomes.
The trade-off is cost versus convenience. DIY credit repair costs only your time. Professional services typically charge monthly fees ranging from $79 to $150, though pricing varies based on the scope of work and the provider’s expertise.
Common Mistakes That Delay Your Progress
Filing vague disputes is the most common error. Simply writing “this is wrong” doesn’t give the bureau enough information to investigate. Effective disputes identify the specific error, explain why it’s incorrect, and provide supporting evidence when available.
Disputing accurate information wastes time and damages credibility. If you genuinely owe the debt and the payment history is correct, no amount of disputing will remove it. Focus your efforts on actual errors and inaccuracies.
Ignoring current accounts while focusing only on old negative items creates a cycle of two steps forward, one step back. New late payments or rising balances cancel out progress made on older items. Maintaining positive payment behavior is essential.
Some people believe closing old accounts or paying off collections immediately improves their score. Closing accounts can actually hurt by reducing your available credit and shortening your credit history. Paying collections removes the debt but doesn’t remove the record, and without a pay-for-delete agreement, it may not improve your score at all.
How Credit Building Complements Repair Efforts
Removing negative items is only half the equation. Building new positive credit accelerates your score improvement. Secured credit cards, credit-builder loans, and becoming an authorized user on someone else’s account all add positive payment history to your report.
Strategic credit building focuses on establishing a mix of credit types, maintaining low utilization, and creating a consistent pattern of on-time payments. Even while disputes are pending, you can open new accounts that begin reporting positive activity immediately.
This two-track approach removes what’s hurting you while simultaneously adding what helps you. The combination produces faster, more substantial score improvements than either strategy alone.
The Connection Between Credit Health and Other Financial Goals
Credit repair often connects to larger financial objectives. Many clients repair their credit specifically to qualify for mortgage loans or business funding. Your credit profile directly impacts your qualification odds and the terms you receive.
If you’re planning to apply for a mortgage, understanding the connection between credit repair and loan approval helps you plan your timeline. Lenders typically want to see at least six months of improved credit behavior after negative items are resolved, so starting your repair process early is crucial.
Similarly, business owners seeking funding need both personal and business credit in good standing. The same dispute principles apply to business credit reports, though the bureaus and processes differ slightly. Coordinating personal credit repair with business credit management creates the strongest foundation for funding applications.
Legal Protections and Your Rights as a Consumer
The Fair Credit Reporting Act gives you specific rights. Credit bureaus must investigate disputes within 30 days. Information proven inaccurate must be corrected or deleted. You can add a 100-word statement to your report explaining disputed items.
The Fair Debt Collection Practices Act protects you from abusive collection practices. Collectors cannot harass you, lie about what you owe, or report information they know is false. If a collector violates these rules, you have legal recourse and the reported item becomes easier to dispute.
Beware of credit repair companies that promise guaranteed results, charge upfront fees before performing services, or advise you to dispute accurate information. These practices violate the Credit Repair Organizations Act. Legitimate services operate transparently, explain your rights, and work within legal boundaries.
Your Path to Better Credit Starts With Understanding the Process
Credit repair is neither magic nor mystery. It’s a methodical process of correcting errors, negotiating with creditors, and building positive payment history. Results take time, but they’re achievable for anyone willing to follow the process consistently.
Most people see initial improvements within 45 to 60 days and reach their target scores within six months. Complex situations may take longer, but steady progress is possible when you combine accurate disputes with smart credit-building strategies and responsible financial behavior.
Quick Tax and Credit Solutions Inc has guided clients through this process for over 20 years, combining credit repair with comprehensive financial services that address the full picture of your financial health. Whether you need help identifying errors, filing disputes, or coordinating your credit repair with tax preparation and business funding goals, professional guidance makes the process smoother and more effective. Call +12146471669 to schedule a consultation and take the first step toward the credit score you deserve.