When you start accepting credit cards, your tax accounting credit cards approach must account for merchant fees, processing delays, and proper revenue recognition timing. The IRS considers credit card sales as cash-equivalent transactions, meaning you recognize income when the customer pays, not when funds settle in your bank account. Processing fees are fully deductible business expenses, but you need proper documentation and categorization to claim them correctly.
Why Payment Processing Creates New Accounting Challenges
Most small businesses start with cash and checks. The accounting is straightforward: money comes in, you record it. Credit card processing introduces a third party between you and your revenue. Every transaction now involves fees, settlement delays, chargebacks, and reconciliation between gross sales and net deposits.
Your bank statement shows deposits that are already reduced by merchant fees. If you only record what hits your account, you understate both income and expenses. That creates problems during tax preparation when your reported sales don’t match your 1099-K forms or when you miss thousands in deductible processing costs.
How the IRS Views Credit Card Revenue
The IRS uses the constructive receipt doctrine for credit card sales. You have constructive receipt of income when it becomes available to you, even if you don’t physically hold it yet. When a customer swipes their card on Monday, you’ve received that income on Monday, even though the money might not appear in your account until Wednesday.
This timing matters for cash-basis taxpayers. If a customer pays by credit card on December 30th but the funds settle January 2nd, that income belongs in the prior tax year. Your point-of-sale system and bookkeeping records need to capture transaction dates, not just deposit dates.
Recording Gross Sales vs Net Deposits
The most common mistake businesses make is recording only the net amount deposited after fees. Here’s the correct approach: record the full sale amount as revenue, then record the merchant fee as a separate expense. A $100 sale with a 2.9% fee should appear as $100 in revenue and $2.90 in merchant service fees, not $97.10 in revenue.
This method accomplishes three things. First, your revenue matches your sales reports and 1099-K forms. Second, you capture the full deductible amount of processing fees. Third, you can track your effective processing rate and negotiate better terms when you see the total annual cost.
Deducting Credit Card Processing Fees for Texas Businesses
Every merchant fee is a fully deductible ordinary and necessary business expense. For businesses operating in Texas, these fees typically run between 1.5% and 3.5% of each transaction, plus monthly gateway fees, terminal rentals, and chargeback costs. Over a year, these expenses add up to significant deductions.
Categorize these fees correctly in your accounting system. Don’t lump them into “bank fees” or “miscellaneous expenses.” Create a dedicated account called “merchant services fees” or “credit card processing fees.” This makes it easier to track costs, compare processors, and provide clean documentation if the IRS ever asks questions.
Setting Up Your Chart of Accounts for Payment Processing
Your chart of accounts needs specific categories to handle credit card transactions properly. At minimum, create these accounts: Credit Card Sales Revenue, Cash Sales Revenue, Merchant Service Fees, Chargeback Expenses, and Credit Card Clearing Account.
The clearing account is particularly important. When you process a sale, the entry debits the clearing account and credits sales revenue. When the deposit hits your bank account, you debit your bank account and credit the clearing account for the net amount, then debit merchant fees and credit the clearing account for the fee portion. This keeps your books balanced and your revenue accurate.
Monthly Reconciliation Best Practices
Reconcile your merchant account every month, just like your bank account. Pull your processor’s monthly statement and compare total sales, total fees, and total chargebacks against your accounting records. The numbers should match exactly.
If they don’t match, find the discrepancy before moving forward. Common issues include duplicate entries, missed transactions, incorrectly categorized refunds, and timing differences at month-end. Small errors compound quickly. A $50 discrepancy in January becomes a $600 year-end problem that takes hours to untangle.
Many business owners discover reconciliation errors only when tax season arrives, forcing last-minute corrections that delay filings. If you’re struggling with monthly reconciliation, the insights in our guide on fixing bookkeeping mistakes before tax season can help you establish better systems now.
Understanding Form 1099-K Reporting Requirements
Payment processors send Form 1099-K to businesses that process more than $5,000 in credit card payments annually, though this threshold is changing. The form reports your gross payment volume, meaning total sales before fees. The IRS receives a copy too.
Your tax return must reconcile with your 1099-K. If the form shows $150,000 in payments but your return only reports $145,000, expect questions. Common reconciliation differences include refunds, chargebacks, and payments for non-business purposes. Document these differences clearly in your tax records.
Step-by-Step Process for Recording a Credit Card Sale
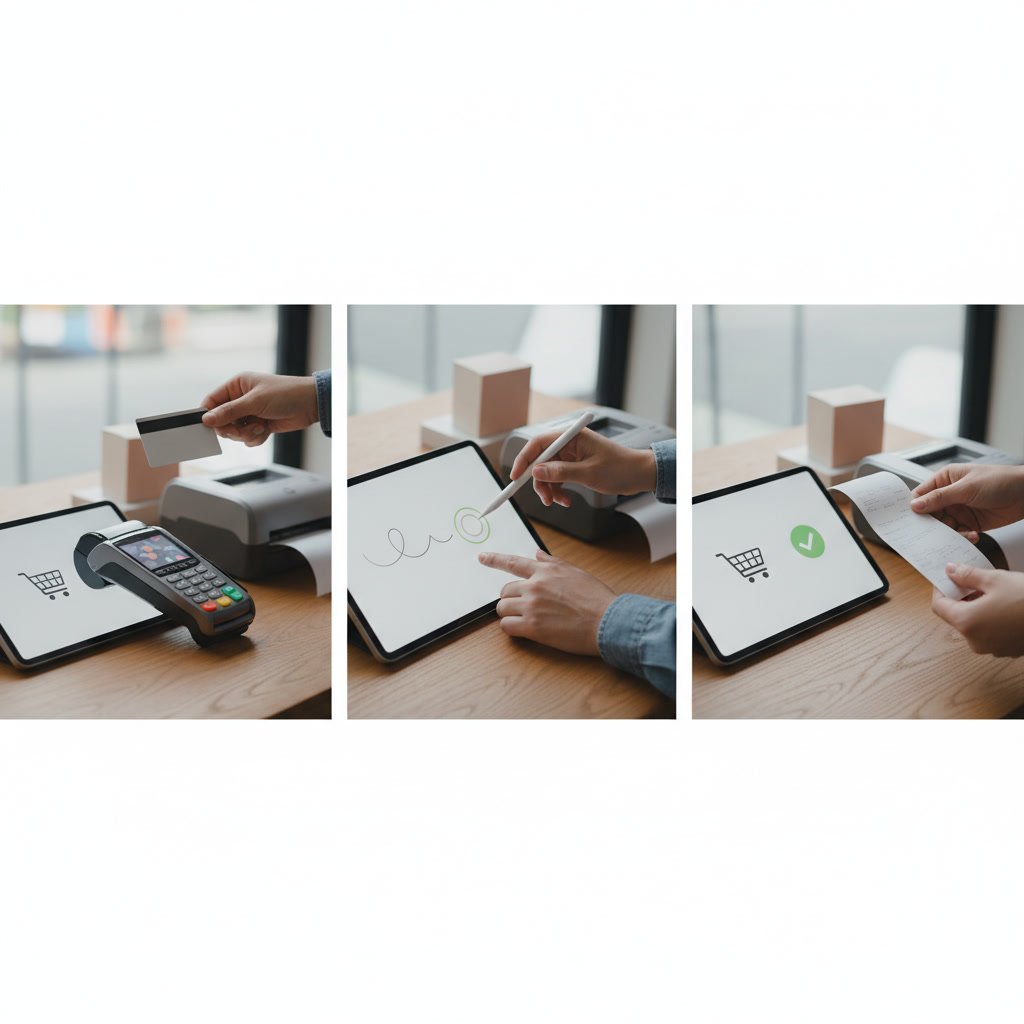
Here’s the exact process for recording credit card transactions in your accounting system:
Step 1: When the sale occurs, record the full sale amount as revenue. Don’t reduce it by the processing fee yet. If you sell $500 in goods, record $500 in sales revenue.
Step 2: Record the merchant fee as a separate expense on the same date. If the processor charges 3%, record $15 as merchant service fees.
Step 3: When the deposit appears in your bank account, record it as a bank deposit for the net amount. Your bank shows $485, which equals the $500 sale minus the $15 fee.
Step 4: Match the deposit to the original sale and fee entries in your accounting system. This completes the transaction cycle and keeps your books balanced.
Step 5: At month-end, verify that your total deposits plus total fees equal your total recorded sales. This is your reconciliation check.
Handling Refunds and Chargebacks Correctly
Refunds reduce your revenue. When you issue a credit card refund, reverse the original sale entry by recording negative revenue. The processor typically refunds their fee too, so record a negative merchant fee expense. Your accounting should mirror exactly what happened: the sale reversed.
Chargebacks are different. A chargeback is both a revenue reversal and an additional fee. If a customer disputes a $100 charge and wins, you lose the $100 sale plus a chargeback fee, often $15 to $25. Record the $100 as negative revenue and the chargeback fee as a separate expense in a dedicated chargeback category.
Special Considerations for Multi-State Operations
Businesses operating across state lines face additional complexity. Sales tax requirements vary by state, and credit card processors don’t always break down sales by location. If you operate in both Texas and Florida, you need systems that track where each sale occurred to properly remit sales tax.
Some point-of-sale systems tag transactions by location automatically. Others require manual tracking. Either way, your business tax filling needs accurate state-by-state revenue reporting. Commingled sales data creates compliance headaches and potential penalties.
Building Systems That Grow With Your Business
The accounting system that works when you process $5,000 monthly in credit cards breaks down at $50,000. Plan ahead. Choose accounting software that integrates directly with your payment processor. QuickBooks, Xero, and similar platforms can import transactions automatically, reducing manual entry and errors.
Automation becomes critical as volume increases. Manual entry of hundreds of transactions monthly is inefficient and error-prone. Integration means your sales data flows directly from your processor to your accounting system with fees already separated. You still need to review and reconcile, but the heavy lifting happens automatically. Quick Tax and Credit Solutions Inc helps businesses in Texas and Florida establish these systems before they become overwhelmed by transaction volume.
As your business grows, the decision of whether to manage this internally or get professional help becomes important. The complexity of payment processing, sales tax, and multi-state operations often reaches a point where hiring a tax consultant saves more money than it costs.
Setting Your Business Up for Clean Records and Maximum Deductions
Proper credit card accounting protects you during audits, maximizes deductions, and provides accurate financial data for business decisions. Record gross sales separately from fees, reconcile monthly, maintain clean category separation, and ensure your records match third-party reporting forms. These practices become routine quickly and prevent expensive problems later.
Whether you’re processing your first credit card payment or handling thousands of transactions monthly, Quick Tax and Credit Solutions Inc provides the tax and accounting expertise to keep your records accurate and compliant. Our team understands the specific challenges payment processing creates and builds systems that work for businesses at every stage. Call us at +12146471669 to discuss how we can help you establish clean accounting practices that save time and maximize your deductions.